
Four insurers dominate private health cover for English-speaking residents in Barcelona: Sanitas, Adeslas, Asisa and DKV, with Cigna and Caser close behind. The right choice hinges on the cuadro médico (network of contracted clinics and specialists) covering your postcode, not the monthly premium.
Here is the decision in one line: pick by network density in your barri first, English-language access second, price third. Premiums for a healthy 30-something sit roughly between €45 and €90 a month across the big names, a gap small enough that an extra metro ride per appointment can wipe it out in year two.
Quick pick: which insurer for which reader
| Insurer | Monthly premium (healthy 30-something, indicative) | Best for | Catch |
|---|---|---|---|
| Sanitas | €55–€90 | English-first customer service, Bupa-owned international reach | Often the priciest of the big names |
| Adeslas | €45–€75 | Families, widest specialist choice in Catalonia per its own published directory | English support depends on the operator |
| Asisa | €50–€80 | One-ecosystem cover via its HLA hospital group | Smaller external network than Adeslas |
| DKV | €50–€90 | App and digital experience, dental on lower tiers | Tends to push you towards its own centres |
Treat these as ranges, not quotes. Price moves meaningfully with your age, postcode and cover tier, and there is no national flat rate, so get a personalised quote from each insurer before you decide. As a sanity check, Sanitas advertises its no-copago hospital plan from roughly €66 a month, which sits mid-band against the range above (Sanitas no-copago plans).
What to compare before you sign (network, waiting periods, copay)
Premium is the easy number. The harder ones make the difference in year two.
Cuadro médico: check your postcode, not the city
Each insurer publishes a directory of contracted clinics and specialists. Pull up the cuadro for your district before you sign. If your nearest gynaecologist on the policy is in Sants and you live in Gràcia, you will feel that on a Tuesday morning at 8am. This is also the community view: long-time DKV members repeatedly note you get funnelled into DKV's own centres, so a thin local network is a real cost, not a footnote. The directories are searchable online: Sanitas, Adeslas, Asisa and DKV.
Carències: waiting periods before cover kicks in
Carències (waiting periods) apply to specific treatments. On a standard retail policy the pattern published by the big insurers typically runs around six months for surgery and complex diagnostics, eight to ten months for childbirth, and longer for fertility, though exact terms sit in each policy's condiciones generales. If you might need any of these in your first year, ask explicitly whether the carència can be waived. It often can, via a corporate quote or proof of continuous prior cover, and the consensus in Barcelona's English-speaking community is that company policies routinely strip the waiting periods out. The waiver is also the default on policies sold specifically for residency visas (see below).
Dental: only the annual check-up is free on a base policy
Most basic policies include only an annual check-up plus discounted-tariff treatments. Fillings and crowns are still chargeable at the network rate. The community view is blunt: no insurer covers dental properly, and the paid add-on still leaves you with mostly basic treatment. A separate dental policy or "Plus" tier costs €10 to €25 a month more; DKV and Cigna include some dental on lower tiers.
Mental health: count the sessions, not the promise
Coverage varies sharply. Some policies give you 20 sessions a year with a network psychologist, some give you 8, some give you only psychiatric consultations and not psychology. If therapy matters to you, ask in writing before signing.
Maternity: which paritori, and after how long
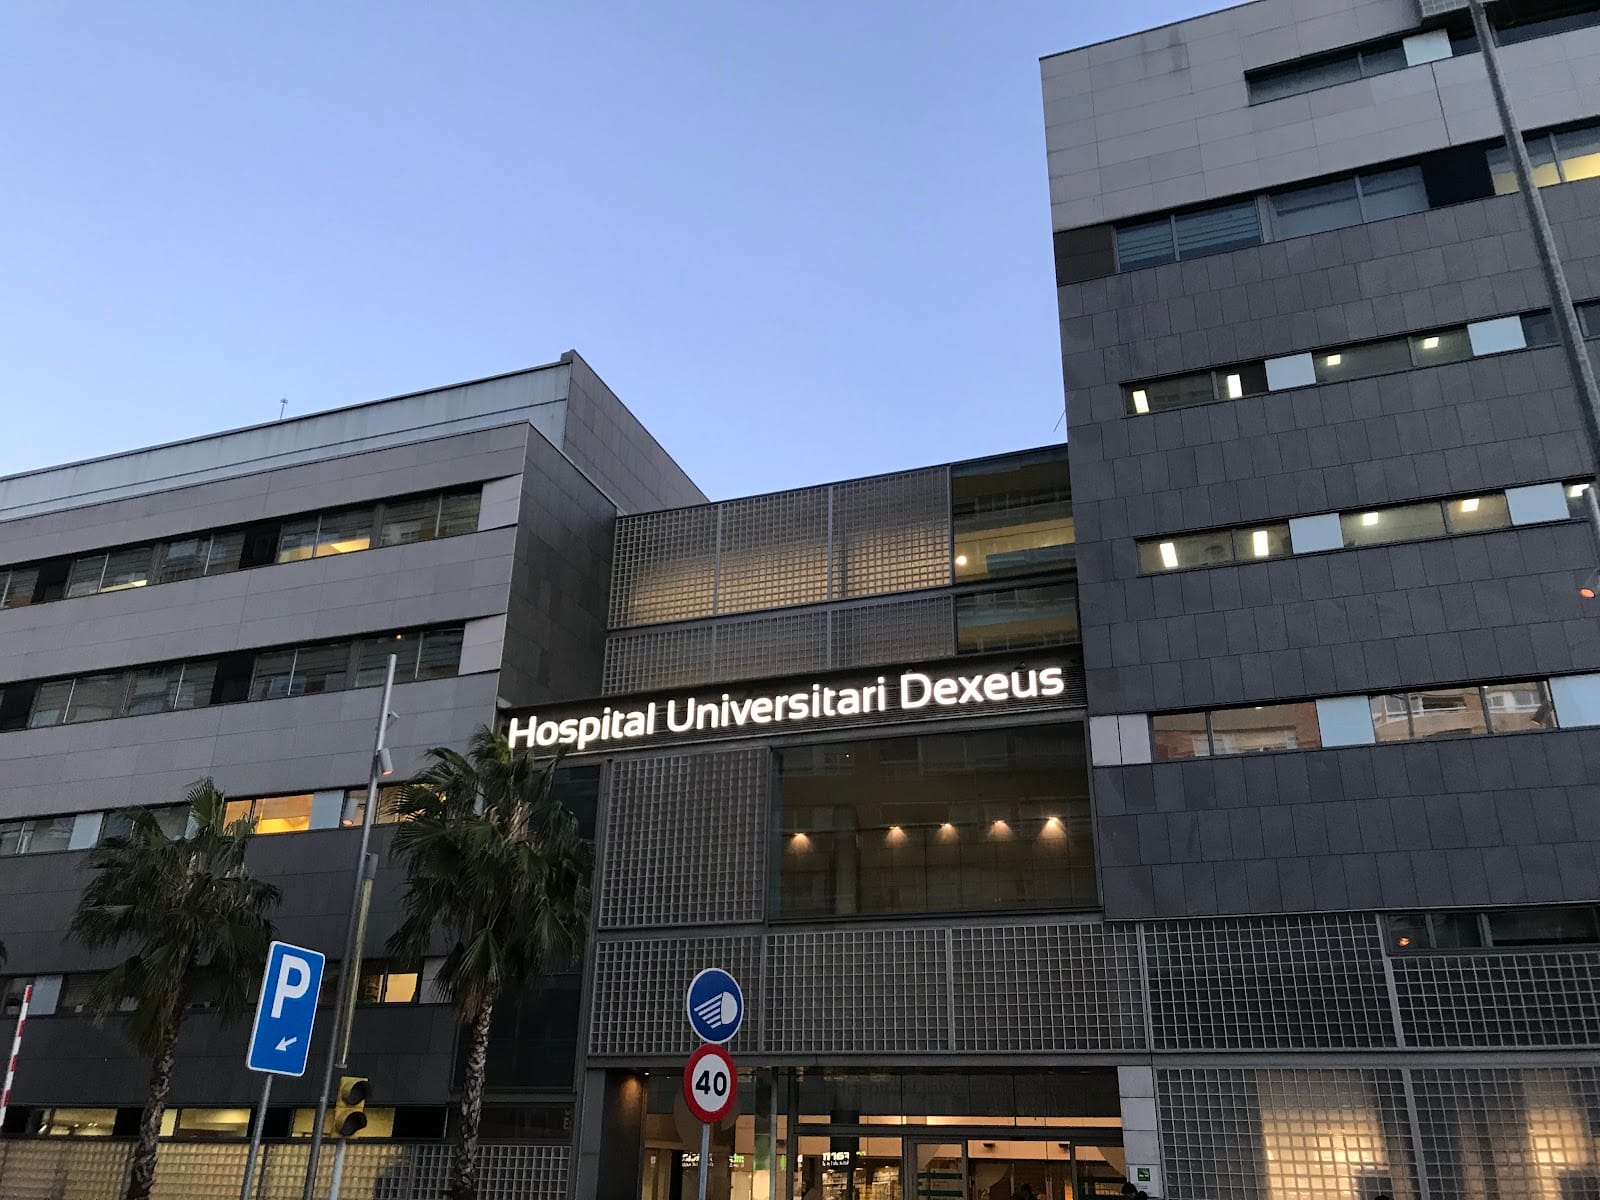
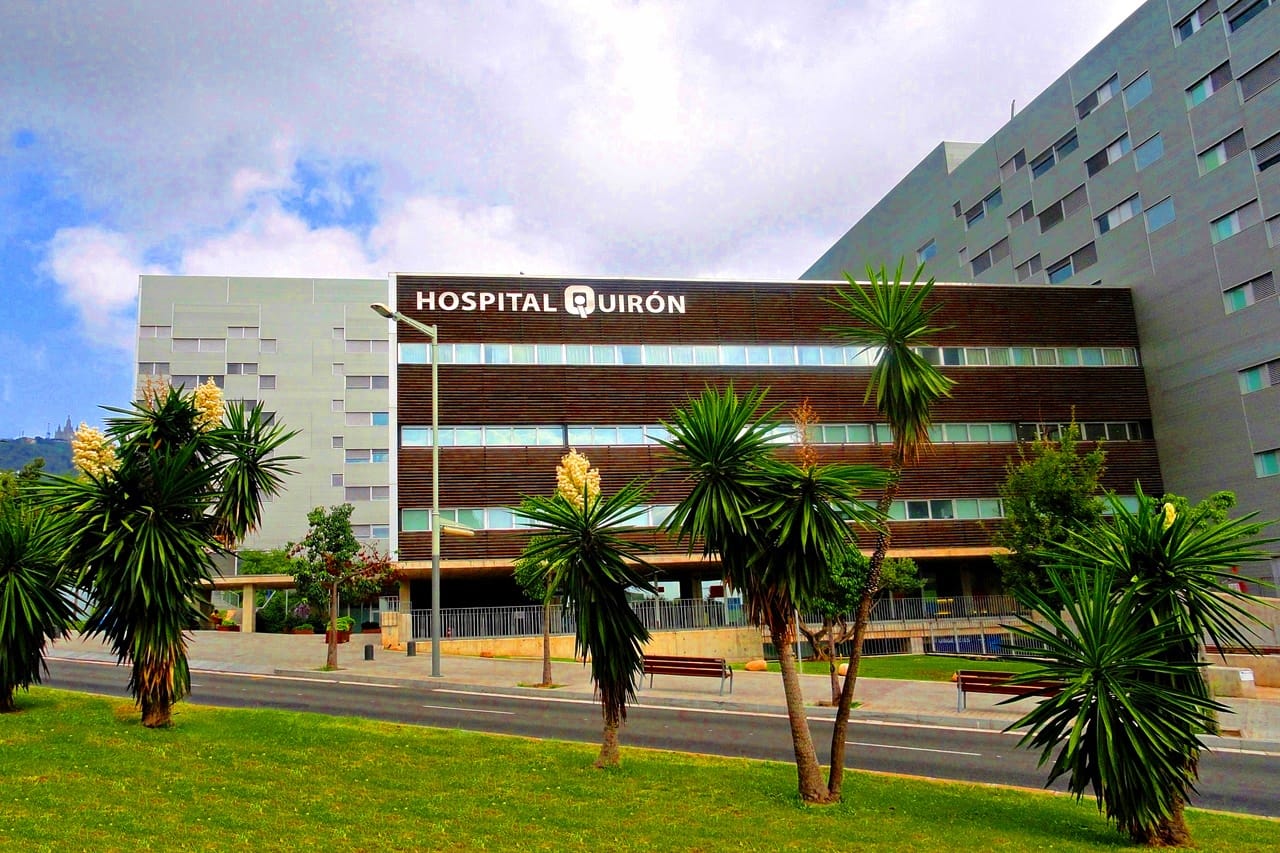
If pregnancy is on the horizon, look at the carència, the network of obstetricians, and whether the policy covers paritori (delivery) at a specific hospital. Sanitas and Adeslas both have strong reputations among Barcelona expats here; Dexeus and Quirón are common preferred hospitals.
Copago: per-visit fee or none
Many policies are sin copago (no per-visit fee). Cheaper variants charge a few euros per consultation, sometimes on a sliding scale and capped at a few hundred euros a year. One thing the community is keen to clarify: sin copago covers procedures and consultations, not prescription medicines, which follow the usual public-pharmacy rules. For visa policies, the no-copago rule is set by the consulate (see below), not the insurer.
Best for / Avoid if
Sanitas: best for English-language-first households and frequent international travellers. Avoid if you are price-sensitive and your postcode is well-served by Adeslas.
Adeslas: best for families wanting the widest specialist choice. Avoid if you need reliable English-language phone support out of hours.
Asisa: best for people who want everything inside the HLA hospital group. Avoid if your preferred specialists are mostly outside it, and read the cancellation terms carefully.
DKV: best for app-first users happy to use DKV's own centres. Avoid if you want free rein across independent clinics, or if your consulate has been slow to recognise smaller insurers in the past.
Visa policies: what the consulate actually requires
If you are applying for a non-lucrative or digital-nomad visa, the consulate wants a certificate from your insurer confirming the policy meets immigration requirements. Sanitas, Adeslas, DKV and Asisa all sell variants designed for this purpose, commonly marketed as a póliza para visado de residencia no lucrativa (a policy specifically issued to meet the residency-visa health-cover rules). Ask the insurer for that product by name, and request the certificado para extranjería in Spanish before you book your consulate appointment. The community tip: ring the insurer, say "I need the one for residency", and they will steer you to the right product.
The legal basis for the cover requirement is Real Decreto 1155/2024, the regulation implementing Spain's immigration law, which replaced Real Decreto 557/2011 on 20 May 2025. Non-lucrative residence now sits in articles 61 to 64, and the substance of the rule is unchanged: the applicant must hold public or private health insurance arranged with an entity authorised to operate in Spain.
Three requirements catch people out. First, the policy normally has to be sin copago (no per-visit fee) for the duration of the visa: even a small GP fee can sink the application. Second, it has to be sin carencias (no waiting periods), so full cover applies from day one, not six months in. Third, it has to match what the Spanish public system provides: full hospitalisation, surgery, ambulance, with no coverage cap. Travel-style policies do not qualify. The good news is that the visa-specific products from the major insurers (for example Sanitas Residents in its sin carencias version, and Adeslas Welcome) are built to clear exactly these three bars, including waiving the waiting periods.
The certificate itself is the document the consulate reads, not your insurance card or an app screenshot, so it needs to say your name, your passport or NIE number, and the words sin copago explicitly. It is normally issued within a few working days of paying the first premium. Each consulate sets its own document list and can interpret edge cases, so confirm the exact wording with the consulate handling your application, and do not pay until that wording matches their checklist.
English-language access: three questions to ask at quote stage
Worth asking three things before you sign.
Is customer service available in English? Sanitas advertises English-language support by default on its English-language site, and its English helpline is one of the most praised things about it in the community. The others are hit-and-miss: Adeslas in particular draws repeated complaints about thin English support, so if phoning in English matters, ask before signing.
Does the cuadro médico flag English-speaking professionals? Some insurer apps now do this (Cigna's directory has long had an English-language filter, for example); with others you have to ring round to confirm. Ask whether the directory has a language filter.
What is the process for getting medical reports translated? Most insurers will not translate, but English-speaking specialists in Barcelona will often write notes in English on request. Worth asking the doctor at the first appointment rather than assuming.
Doctoralia is a useful sense-check: search for a specialty, filter by your insurer's network, and read the recent reviews to spot the doctors who handle English-speaking patients well.
Switching and cancelling: the 30-day window and the carència reset
Most policies renew annually with a 30-day notice period before the renewal date, set out in Article 22 of Ley 50/1980 de Contrato de Seguro, Spain's insurance-contract law. If you want to switch, do it in writing (email or burofax) within the window, otherwise the policy rolls over automatically. Two practical notes from the community: keep written proof and check your card statements, because cancellations can be a fight (one member reported an insurer that kept charging after cancellation); and if your insurer hikes the premium at renewal, threatening to leave for a better quote can claw a large chunk of it back, so make that call before you switch.
Carències usually reset when you change insurer because each contract starts a fresh waiting-period clock, unless the new insurer agrees to waive them on proof of continuous prior cover (a commercial decision, not a legal entitlement). That is the strongest argument against jumping every twelve months for a tenner-a-month saving. Stick with the right policy rather than the cheapest one each year.
Public system context: do you also need to register at your CAP?
Private insurance does not replace the public system, and most expats use both. Once you have your NIE (Número de Identidad de Extranjero, the foreigner ID number) and TIE (Tarjeta de Identidad de Extranjero, the residency card), and you are paying into the Spanish social-security system or qualify via another route, you can register at your local CAP (Centre d'Atenció Primària, the neighbourhood primary-care clinic run by CatSalut) and get a targeta sanitària individual. The official guide to obtaining the card is on CatSalut's site, and the Ajuntament de Barcelona lists CAPs by district. The public system handles emergencies, long-term conditions and vaccinations well; private cover gets you specialists in days rather than months.
What most people miss: the directory is the truth, not the brochure
The lowest premium in the brochure is not always the lowest cost in practice.
A cheap policy with a thin cuadro médico in your district means you will travel further for every appointment, and that gets old fast in year two. Open the directory, find the clinics you would actually use, and let geography decide. The boring answer wins here. The TMB (Transports Metropolitans de Barcelona) metro map is a fair proxy: if the nearest in-network specialist is more than two stops from home, that is the real cost of the cheaper premium.
Also worth knowing: many Barcelona clinics work with multiple insurers, and the same doctor might be in network for Sanitas but out for Adeslas. Before committing, write down the three specialists you would actually use (district GP, an obstetrician or paediatrician if relevant, a dentist), then check each one against the provider's cuadro by name. The directory is the truth, not the brochure.
Community experience, not medical or insurance advice. For anything urgent or unclear, call 061 or 112, or contact your GP.
Are you a Barcelona resident?
Picking an insurer often comes down to which doctors near you take English-speaking patients, and that is exactly the kind of question fellow residents answer best. The Barcelona English Speakers community has 4,000+ members across 20+ free, moderated WhatsApp groups, from healthcare to flat-hunting and neighbourhoods. Come and ask who people actually use before you sign.
This guide's prices and regulations were last verified on 26 September 2026.
Primary sources: Real Decreto 1155/2024 (BOE) · Ley 50/1980 de Contrato de Seguro (BOE) · CatSalut: obtaining the targeta sanitària individual · Ajuntament de Barcelona: CAPs by district · Sanitas: no-copago plan tariffs